Monday, November 2, 2026

Corporate headshot photographer NYC Michael Benabib recently recognized for his work in a one-man show in Tokyo

Corporate headshot photographer NYC Michael Benabib recently recognized for his work in a one-man show in Tokyo
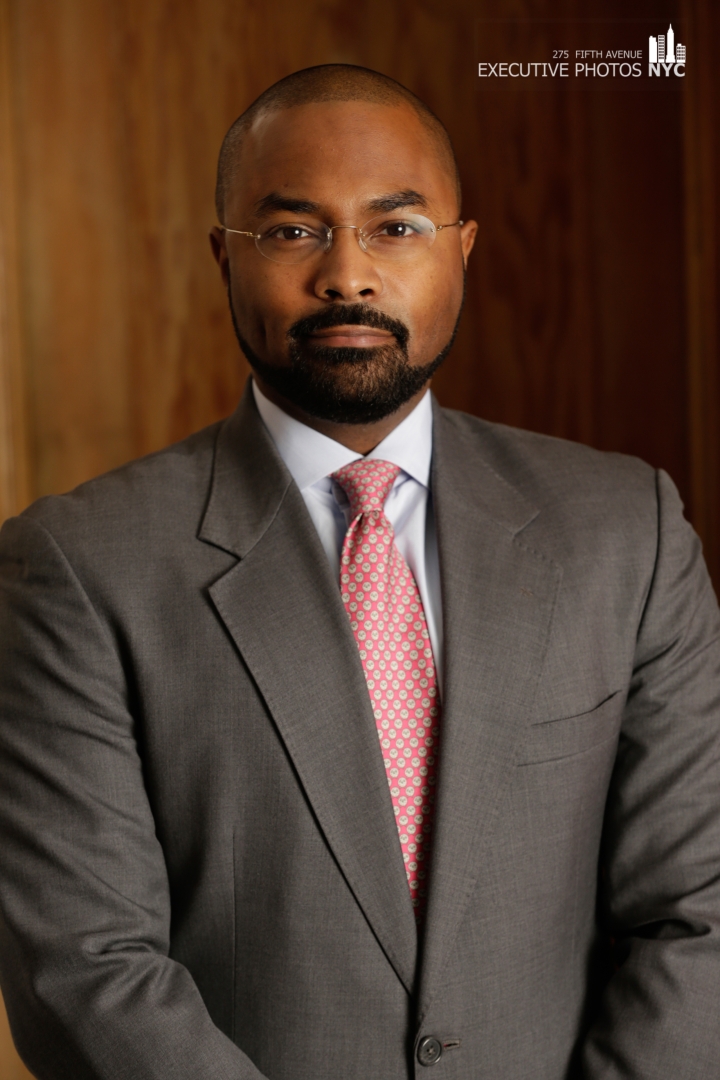
Executive Photos NYC Portrait
Executive Photos NYC founder Michael Benabib, a corporate headshot photographer in New York City, applies an editorial style shaped by Vanity Fair and The New York Times to executive portraits.

NEW YORK, NY - November 2, 2026 - Michael Benabib, the corporate headshot photographer in New York City behind Executive Photos NYC, is expanding studio and on-location executive portrait sessions that apply the editorial approach he developed photographing for Forbes, The New York Times, Vanity Fair and The Wall Street Journal. As a corporate headshot photographer in New York City for more than 30 years, Benabib now photographs Fortune 500 executives, attorneys, physicians and full leadership teams on location and at his studio at 275 Fifth Avenue in Midtown Manhattan.

The expansion follows Benabib's 2026 solo exhibition in Tokyo, a retrospective of three decades of musician and celebrity magazine portraits. His editorial subjects have included David Bowie, Keith Richards, Tupac Shakur and President Bill Clinton, and his photographs are held in the permanent collections of the Smithsonian and the Museum of Modern Art.

From magazine assignments to the corporate headshot

Benabib's corporate headshot practice grew directly out of editorial work. A magazine assignment allows minutes, not hours, with a subject who is often guarded or pressed for time. The photographer has to establish trust quickly, find an unforced expression and finish without disrupting the subject's schedule.

Those same conditions define the modern corporate headshot. Executives, law-firm partners and physicians typically arrive between meetings, uneasy in front of a camera, and need a portrait that reads as credible on a firm website, a LinkedIn profile, a press kit or a speaker biography.

"A magazine portrait and a corporate headshot ask the same question: who is this person, really?" said Benabib. "The legal and financial fields are built on trust. Your portrait is the first place that trust is either established or lost."

Clients and sectors

Executive Photos NYC has photographed executives and teams for American Express, J.P. Morgan, Pfizer, Skanska and ABC News. Notable portrait subjects include former U.S. Attorney General Loretta E. Lynch, attorney Alan Dershowitz and the late Yale investment chief David F. Swensen.

The studio serves finance, legal, medical and industrial clients. Its industrial work has documented major New York City infrastructure projects, including the Second Avenue Subway and Moynihan Train Hall in the former Farley Post Office.

How sessions work

Clients choose between two formats. Studio sessions take place at the Fifth Avenue studio, which includes controlled lighting, a selection of backgrounds, a private changing room and an on-site hair and makeup station. On-location sessions bring a portable studio to a client's conference room, office or trading floor, producing environmental portraits that show a professional in context.

Every session includes on-set review, so clients approve their selects before the shoot ends. Retouched high-resolution files are delivered the next day. Executive Photos NYC is fully insured for access to corporate buildings across Manhattan and works with individuals as well as firm-wide portrait days for 20 or more people, keeping lighting and framing consistent across a whole team.

About Executive Photos NYC

Executive Photos NYC is a corporate headshot and business portrait studio in Midtown Manhattan founded by photographer Michael Benabib. The studio provides executive headshots, LinkedIn headshots, team portraits, on-location environmental portraits and corporate event photography for companies in New York City and nationwide. More information is available at executivephotosnyc.com.

Media contact

Michael Benabib, Executive Photos NYC 275 Fifth Avenue, New York, NY 10016 Phone: 212-683-4853b Website: https://www.executivephotosnyc.com Email : info@executivephotosnyc.com

Media Contact
Company Name: Executive photos nyc
Contact Person: Michael Benabib
Email:Send Email
Phone: 212.683.4853
Address:275 5th Ave
City: NY 10016
State: New York
Country: United States
Website: https://www.executivephotosnyc.com

EGFR Inhibitors-Induced Skin Disorders Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight

EGFR Inhibitors-Induced Skin Disorders Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight
The EGFR Inhibitors-Induced Skin Disorders market analysis report delivers important insights into ongoing research on pipeline EGFR Inhibitors-Induced Skin Disorders drugs, clinical strategies, upcoming therapeutics, and commercial analysis.

(Albany, US) On November 02, 2026, DelveInsight’s “EGFR-Induced Skin Disorders Market Insights, Epidemiology and Market Forecast – 2036” report provides comprehensive insights into the EGFR Inhibitor-Induced Skin Disorders market and pipeline landscape across the 7MM. It covers marketed and emerging drug profiles, including clinical and nonclinical stage products. It also covers the therapeutics assessment by product type, stage, route of administration, and molecule type, and examines the market drivers and barriers shaping the space.

Discover the latest drugs and treatment options in the EGFR Inhibitors-Induced Skin Disorders Pipeline @ EGFR Inhibitors-Induced Skin Disorders market

Key Takeaways from the EGFR Inhibitors-Induced Skin Disorders Report

  • In March 2026, Hoth Therapeutics reported pharmacokinetic, safety, and clinical activity data for HT-001 in cancer patients with EGFR therapy-associated skin toxicities, showing favorable tolerability, no serious adverse events, minimal systemic absorption, and reductions in symptom severity.

  • In September 2025, Hoth submitted a clinical trial application to the EMA to expand its ongoing Phase II trial of HT-001.

  • In August 2025, Azitra announced dosing of the first patient in its Phase I/II trial of ATR04-484 (ATR-04), a topical live biotherapeutic for EGFR inhibitor-associated rash, which holds FDA Fast Track designation.

  • In June 2025, Lutris Pharma presented additional positive Phase II data for LUT-014 gel in acneiform rash associated with anti-EGFR therapies at the ESMO Gastrointestinal Cancers Congress 2025. LUT-014 holds Orphan Drug Designation for EGFR-induced acneiform rash.

  • No therapies are approved specifically for EGFR inhibitor-induced skin disorders, and management relies on supportive care such as topical corticosteroids, emollients, antibiotics, and antihistamines.

  • Dermatologic toxicity affects most patients on EGFR inhibitors, with acneiform rash reported in about 50 to 90% of treated patients. The US holds the largest patient share among the 7MM, with about 13,000 cases in NSCLC in 2025.

  • DelveInsight’s report depicts an early-stage space where the pipeline is expanding toward targeted topical and microbiome-based dermatology-oncology therapies.

  • Leading EGFR Inhibitors-Induced Skin Disorders companies include Lutris Pharma, Hoth Therapeutics, Azitra, and others.

  • Promising therapies include LUT-014, HT-001, ATR-04, and others.

Get insights into clinical trials, emerging therapies, and leading companies with DelveInsight @ EGFR Inhibitors-Induced Skin Disorders market research

EGFR Inhibitors-Induced Skin Disorders Overview

EGFR inhibitor-induced skin disorders are dermatologic toxicities caused by EGFR-targeted therapies used in non-small cell lung, colorectal, head and neck, pancreatic, and breast cancers. EGFR plays a critical role in skin homeostasis, keratinocyte proliferation, and hair follicle function, so inhibiting it produces acneiform rash, dry skin (xerosis), pruritus, eczema, paronychia, fissures, and hair abnormalities. These toxicities affect most treated patients and can impair quality of life, compromise adherence, and force dose changes. Diagnosis is clinical, based on history, timing relative to EGFR inhibitor start, and severity grading using CTCAE. Management is supportive and symptom-based: moisturizers, sunscreen, topical corticosteroids, topical or oral antibiotics (doxycycline, minocycline), antihistamines, and, in severe cases, systemic corticosteroids and dose reduction or interruption.

Common manifestations include:

  • Acneiform (papulopustular) rash

  • Dry skin and fissures

  • Itching (pruritus)

  • Paronychia and nail toxicities

  • Eczema-like reactions and hair abnormalities

EGFR Inhibitors-Induced Skin Disorders Emerging Drugs Profile

LUT-014: Lutris Pharma LUT-014 is a proprietary, first-in-class topical B-Raf inhibitor small molecule being developed for acneiform lesions induced by EGFR inhibitors. It has Orphan Drug Designation for EGFR-induced acneiform rash and has also completed a Phase I study in radiation-induced dermatitis in breast cancer patients. Currently, the drug is in Phase II.

HT-001: Hoth Therapeutics HT-001 is a topical formulation for mild to moderate rash and skin disorders associated with tyrosine kinase inhibitor/EGFR inhibitor therapy, designed to reduce inflammation and restore the skin barrier. The Phase IIa CLEER trial is underway, with interim results highlighting preservation of cancer treatment while resolving skin side effects. Currently, the drug is in Phase II.

ATR-04 (ATR04-484): Azitra ATR-04 is a topical live biotherapeutic product based on an engineered Staphylococcus epidermidis strain, modified to be safer by deleting an antibiotic resistance gene and adding auxotrophy to control its growth. It aims to restore skin microbial balance and barrier function and modulate inflammation in EGFR inhibitor-associated rash. It holds FDA Fast Track designation. Currently, the drug is in Phase I/II.

Explore groundbreaking therapies and clinical trials in the EGFR Inhibitors-Induced Skin Disorders Pipeline @ EGFR Inhibitors-Induced Skin Disorders market insight

EGFR Inhibitors-Induced Skin Disorders Market Drivers

  • Expanding EGFR inhibitor use: Wider adoption across NSCLC, colorectal, pancreatic, head and neck, and breast cancers is increasing the population exposed to skin toxicities.

  • High toxicity burden: Dermatologic adverse events occur in most treated patients and affect adherence, dose intensity, and quality of life.

  • No approved disease-specific therapy: The absence of targeted options creates a clear opening for new entrants.

  • Targeted, differentiated pipeline: Topical kinase inhibitors, skin barrier restoration agents, and microbiome-based therapies address underlying mechanisms rather than symptoms alone.

  • Regulatory support: Orphan Drug Designation and Fast Track designations support development.

  • Oncology-dermatology crossover: Growing focus on keeping patients on anticancer therapy is increasing demand for supportive-care innovation.

  • Strong US market conditions: High EGFR therapy use, strong oncology infrastructure, and rapid adoption of supportive care products favor commercial uptake.

Learn about new drugs, pipeline developments, and key players with DelveInsight’s expert analysis @ EGFR Inhibitors-Induced Skin Disorders market trends

EGFR Inhibitors-Induced Skin Disorders Market Barriers

  • Entrenched low-cost supportive care: Generic corticosteroids, emollients, and tetracycline antibiotics are widely used and inexpensive.

  • Early-stage pipeline: Candidates are in Phase I/II or Phase II, with clinical and regulatory risk and limited head-to-head evidence.

  • Preserving anticancer efficacy: New topicals must show they do not interfere with EGFR inhibitor activity.

  • Lack of biomarkers and standard algorithms: The absence of predictive biomarkers and standardized treatment makes patient selection and trial design harder.

  • Fragmented patient pool: Cases are spread across several cancer types and EGFR therapies, complicating recruitment and commercial targeting.

  • Reactive treatment patterns: Management is largely reactive, and prophylactic use of new products may need new guidelines.

  • Reimbursement uncertainty: Payers may question paying for premium supportive-care products against inexpensive alternatives.

Scope of the EGFR Inhibitors-Induced Skin Disorders Report

  • Coverage: 7MM (US, EU4, UK, Japan)

  • Companies: As listed above

  • Therapies: LUT-014, HT-001, ATR-04, and others

  • Assessment by Product Type: Mono, Combination, Mono/Combination

  • Assessment by Clinical Stage: Discovery, Pre-clinical, Phase I, Phase II, Phase III

Download DelveInsight’s in-depth EGFR Inhibitors-Induced Skin Disorders report

Table of Contents

  1. Introduction

  2. Executive Summary

  3. EGFR Inhibitors-Induced Skin Disorders: Overview

  4. Pipeline Therapeutics

  5. Therapeutic Assessment

  6. DelveInsight’s Analytical Perspective

  7. Late Stage Products (Phase III): None currently

  8. Mid Stage Products (Phase II): LUT-014 (Lutris Pharma), HT-001 (Hoth Therapeutics)

  9. Early Stage Products (Phase I): ATR-04 (Azitra), Phase I/II

  10. Preclinical and Discovery Stage Products

  11. Inactive Products

  12. Key Companies

  13. Key Products

  14. Unmet Needs

  15. Market Drivers and Barriers

  16. Future Perspectives and Conclusion

  17. Analyst Views

  18. Appendix

  19. About Us

About DelveInsight DelveInsight is a leading healthcare-focused market research and consulting firm that provides clients with high-quality market intelligence and analysis to support informed business decisions. With a team of experienced industry experts and a deep understanding of the life sciences and healthcare sectors, we offer customized research solutions and insights to clients across the globe.

Media Contact
Company Name: DelveInsight Business Research LLP
Contact Person: Mehul Malhotra
Email:Send Email
Phone: +19193216187
Address:304 S. Jones Blvd #2432
City: Albany
State: New York
Country: United States
Website: https://www.delveinsight.com/consulting

Granulomatosis With Polyangiitis Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight

Granulomatosis With Polyangiitis Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight
The Granulomatosis With Polyangiitis market analysis report delivers important insights into ongoing research on pipeline Granulomatosis With Polyangiitis drugs, clinical strategies, upcoming therapeutics, and commercial analysis.

(Albany, US) On November 02, 2026, DelveInsight’s “Granulomatosis with Polyangiitis Market Insights, Epidemiology and Market Forecast – 2036” report provides comprehensive insights into the Granulomatosis with Polyangiitis (GPA) market and pipeline landscape across the 7MM. It covers marketed and emerging drug profiles, including clinical and nonclinical stage products. It also covers the therapeutics assessment by product type, stage, route of administration, and molecule type, and examines the market drivers and barriers shaping the space.

Discover the latest drugs and treatment options in the Granulomatosis With Polyangiitis Pipeline @ https://www.delveinsight.com/report-store/granulomatosis-with-polyangiitis-market

Key Takeaways from the Granulomatosis With Polyangiitis Report

  • In June 2026, the EMA’s CHMP recommended revoking the EU marketing authorization for TAVNEOS (avacopan). The review concluded the pivotal ADVOCATE trial breached good clinical practice, rendering the efficacy data unreliable, and cited safety risks including drug-induced liver injury and vanishing bile duct syndrome.

  • In June 2026, Amgen announced new data presentations at EULAR 2026, including real-world evidence on avacopan’s efficacy and safety with reduced steroid use in ANCA-associated vasculitis.

  • In October 2025, GSK outlined planned regulatory milestones for depemokimab in eosinophilic granulomatosis with polyangiitis (EGPA) for H2 2026.

  • GPA is the most prevalent form of ANCA-associated vasculitis (AAV), with an estimated annual incidence of about 10 to 20 cases per million, and PR3-ANCA-positive disease represents about three-quarters of diagnosed cases.

  • DelveInsight’s report depicts a space shifting from broad immunosuppression toward targeted, steroid-sparing therapies, with the US the largest market among the 7MM in 2025.

  • Leading Granulomatosis With Polyangiitis companies include GSK, Amgen, NS Pharma, and others.

  • Promising therapies include depemokimab, SHR-1703, avacopan (TAVNEOS), NS-229, rituximab (RITUXAN), and others.

Get insights into clinical trials, emerging therapies, and leading companies with DelveInsight @ Granulomatosis With Polyangiitis market

Granulomatosis With Polyangiitis Overview

GPA, formerly known as Wegener’s granulomatosis, is a rare systemic autoimmune disorder characterized by necrotizing inflammation of small- to medium-sized blood vessels and granuloma formation, primarily affecting the upper respiratory tract, lungs, and kidneys. It belongs to the group of ANCA-associated vasculitides, with most patients testing positive for PR3-ANCA. Diagnosis combines clinical presentation, ANCA serology, imaging, and tissue biopsy when feasible. Treatment is divided into induction and maintenance. Severe disease is typically induced with rituximab or cyclophosphamide plus glucocorticoids, and maintenance uses rituximab, azathioprine, or methotrexate. Relapse, cumulative organ damage, and long-term corticosteroid toxicity remain key challenges.

Common manifestations include:

  • Chronic sinusitis, nasal crusting, or ulcers

  • Cough, hemoptysis, and pulmonary nodules

  • Rapidly progressive glomerulonephritis

  • Musculoskeletal, ocular, and skin involvement

  • Peripheral nervous system involvement

Granulomatosis With Polyangiitis Emerging Drugs Profile

Depemokimab: GSK Depemokimab is an ultra-long-acting anti-IL-5 monoclonal antibody for eosinophil-driven inflammatory diseases, including EGPA. By inhibiting IL-5, a cytokine central to eosinophil growth and survival, it aims to provide sustained suppression of eosinophilic inflammation with less frequent dosing, reduce relapses, and lower corticosteroid dependence. It is given subcutaneously. Currently, the drug is in Phase III.

NS-229: NS Pharma NS-229 is an investigational oral, selective JAK1 inhibitor for EGPA. By modulating cytokine signaling involved in eosinophilic inflammation and immune activation, it aims to reduce vascular inflammation, control disease activity, and decrease corticosteroid dependence. Currently, the drug is in a global Phase II trial.

Explore groundbreaking therapies and clinical trials in the Granulomatosis With Polyangiitis Pipeline @ Granulomatosis With Polyangiitis market research

Granulomatosis With Polyangiitis Market Drivers

  • Shift to targeted, steroid-sparing therapy: Rituximab and avacopan have moved care away from broad immunosuppression, and the aim is to improve remission, cut relapses, and limit glucocorticoid exposure.

  • Better recognition and diagnosis: Growing awareness of AAV, wider ANCA testing, and improved imaging support earlier diagnosis and a larger identified patient population.

  • Precision diagnostics and monitoring: ANCA serology, refined classification criteria, and better disease monitoring improve patient stratification and early relapse detection.

  • Active pipeline: Depemokimab and NS-229 target eosinophilic and cytokine-driven pathways, and SHR-1703 is also in development.

  • Large unmet need: Persistent relapse, cumulative organ damage, and long-term steroid toxicity sustain demand for safer, more durable options.

  • Increasing biologic adoption: Rituximab is guideline-supported for induction and maintenance in moderate-to-severe disease.

Learn about new drugs, pipeline developments, and key players with DelveInsight’s expert analysis @ Granulomatosis With Polyangiitis market insight

Granulomatosis With Polyangiitis Market Barriers

  • Safety and regulatory uncertainty for avacopan: The proposed EU revocation, citing data reliability and safety concerns, could weaken the leading steroid-sparing option.

  • High treatment costs and reimbursement constraints: These may moderate uptake of newer agents.

  • Entrenched rituximab: Broad physician familiarity and a well-established profile set a high bar for new entrants.

  • Rarity of the disease: A small patient population limits trial recruitment and commercial scale.

  • Limited biomarkers: There are few reliable markers of disease activity and relapse prediction.

  • Long-term immunosuppression risks: Infection burden and cumulative toxicity limit the benefit of current regimens.

  • Pipeline focus on EGPA: Both profiled late- and mid-stage candidates target EGPA, so GPA-specific evidence is still limited.

Scope of the Granulomatosis With Polyangiitis Report

  • Coverage: 7MM (US, EU4, UK, Japan)

  • Companies: As listed above

  • Therapies: Depemokimab, SHR-1703, avacopan (TAVNEOS), NS-229, rituximab (RITUXAN), and others

  • Assessment by Product Type: Mono, Combination, Mono/Combination

  • Assessment by Clinical Stage: Discovery, Pre-clinical, Phase I, Phase II, Phase III

Download DelveInsight’s in-depth Granulomatosis With Polyangiitis report today! @ Granulomatosis With Polyangiitis market trends

Table of Contents

  1. Introduction

  2. Executive Summary

  3. Granulomatosis With Polyangiitis: Overview

  4. Pipeline Therapeutics

  5. Therapeutic Assessment

  6. DelveInsight’s Analytical Perspective

  7. Late Stage Products (Phase III): Depemokimab (GSK)

  8. Mid Stage Products (Phase II): NS-229 (NS Pharma)

  9. Early Stage Products (Phase I): None currently

  10. Preclinical and Discovery Stage Products

  11. Inactive Products

  12. Key Companies

  13. Key Products

  14. Unmet Needs

  15. Market Drivers and Barriers

  16. Future Perspectives and Conclusion

  17. Analyst Views

  18. Appendix

  19. About Us

About DelveInsight DelveInsight is a leading healthcare-focused market research and consulting firm that provides clients with high-quality market intelligence and analysis to support informed business decisions. With a team of experienced industry experts and a deep understanding of the life sciences and healthcare sectors, we offer customized research solutions and insights to clients across the globe.

Media Contact
Company Name: DelveInsight Business Research LLP
Contact Person: Mehul Malhotra
Email:Send Email
Phone: 09650213330
Address:63, M3M 113 Market, Sector 113 NV 89107
City: Gurugram
State: IN - Indiana
Country: India
Website: https://www.delveinsight.com/consulting

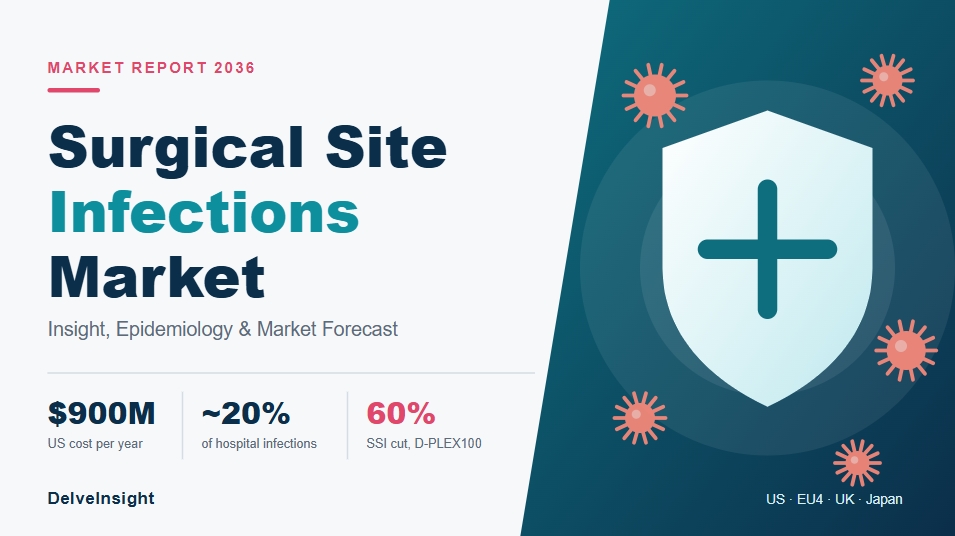
Surgical Site Infections Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight

Surgical Site Infections Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight
The Surgical Site Infections market analysis report delivers important insights into ongoing research on pipeline Surgical Site Infections drugs, clinical strategies, upcoming therapeutics, and commercial analysis.

(Albany, US) On November 02, 2026, DelveInsight’s “Surgical Site Infections Market Insights, Epidemiology and Market Forecast – 2036” report provides comprehensive insights into the Surgical Site Infections (SSI) market and pipeline landscape across the 7MM. It covers marketed and emerging drug profiles, including clinical and nonclinical stage products. It also covers the therapeutics assessment by product type, stage, route of administration, and molecule type, and examines the market drivers and barriers shaping the space.

Discover the latest drugs and treatment options in the Surgical Site Infections Pipeline @ https://www.delveinsight.com/report-store/surgical-site-infections-ssi-market

Key Takeaways from the Surgical Site Infections Report

  • In June 2026, PolyPid announced completion of its rolling NDA submission to the US FDA for D-PLEX100 for the prevention of SSIs in patients undergoing colorectal surgery. The company anticipates a potential FDA decision in Q1 2027 under the PDUFA timeline.

  • In May 2026, PolyPid presented ASEPSIS score data from its Phase III SHIELD II trial of D-PLEX100 at the 45th Annual Meeting of the Surgical Infection Society, and in April 2026 it presented new pharmacokinetic data at ESCMID Global 2026.

  • In SHIELD II, D-PLEX100 showed a statistically significant 60% reduction in incisional SSIs compared with standard of care alone. It holds FDA Fast Track, Breakthrough Therapy, and QIDP designations.

  • In May 2026, AMR Bio announced it is advancing XF-73 toward Phase III development. XF-73 holds QIDP and Fast Track designations.

  • In March 2026, Ondine announced that its North American Phase III study of nasal photodisinfection had reached more than 93% enrollment, bringing it closer to FDA submission.

  • Olanexidine gluconate (OLANEDINE, Otsuka Pharmaceutical), approved in Japan in 2015, is the only approved SSI-specific product. None are approved in the US, Europe, or other major markets.

  • In the US, SSIs are associated with over 400,000 additional hospitalization days each year, at an estimated excess cost of USD 900 million.

  • Leading Surgical Site Infections companies include Otsuka Pharmaceutical, PolyPid, AMR Bio, and others.

  • Promising therapies include olanexidine gluconate (OLANEDINE), D-PLEX100, XF-73, STERIWAVE, and others.

Get insights into clinical trials, emerging therapies, and leading companies with DelveInsight @ Surgical Site Infections market

Surgical Site Infections Overview

Surgical site infections occur at or near a surgical incision within 30 days of a procedure, or within one year if an implant is placed, and are among the most common healthcare-associated infections. They can involve the skin, subcutaneous tissue, deep soft tissues, organs, or surgical spaces. Common pathogens include Staphylococcus aureus, coagulase-negative staphylococci, Enterococcus species, and gram-negative bacteria. SSIs lead to prolonged hospitalization, higher costs, reoperations, and increased morbidity and mortality. Diagnosis is mainly clinical, supported by wound cultures and, for deep infections, imaging. The current standard of care is largely preventive, relying on perioperative antibiotic prophylaxis (such as cefazolin, vancomycin, and clindamycin), antiseptic skin preparation, sterile technique, and postoperative wound care.

Common signs and symptoms include:

  • Redness, swelling, and warmth at the surgical site

  • Pain or tenderness

  • Purulent drainage

  • Wound dehiscence

  • Fever

Surgical Site Infections Emerging Drugs Profile

D-PLEX100: PolyPid D-PLEX100 is built on PolyPid’s proprietary PLEX (Kynatrix) technology, providing sustained local release of doxycycline at the surgical site for up to 30 days, with activity against both gram-positive and gram-negative bacteria. In the Phase III SHIELD II trial, it reduced incisional SSIs by 60% versus standard of care alone. It holds FDA Fast Track, Breakthrough Therapy, and QIDP designations, and a potential FDA decision is anticipated in Q1 2027. Currently, the drug is in Phase III, with an NDA submitted.

XF-73: AMR Bio XF-73 is a first-in-class, porphyrin-based intranasal antimicrobial gel designed for pre-surgical decolonization of Staphylococcus aureus, including MRSA, a leading cause of SSIs. It holds QIDP and Fast Track designations. Currently, the drug is advancing toward Phase III.

STERIWAVE: Ondine STERIWAVE is a non-antibiotic nasal photodisinfection technology that eradicates pathogens in the nasal cavity before surgery. Its North American Phase III study had passed 93% enrollment as of March 2026.

Explore groundbreaking therapies and clinical trials in the Surgical Site Infections Pipeline @ Surgical Site Infection control market

Surgical Site Infections Market Drivers

  • Growing surgical volumes: Aging populations, chronic disease, and expanding healthcare access are increasing the number of patients at risk.

  • Antimicrobial resistance: MRSA and multidrug-resistant organisms are driving interest in prevention technologies that reduce reliance on conventional antibiotics.

  • Quality and regulatory initiatives: Stricter infection-control guidelines, quality metrics, and WHO recognition of SSIs as a major global health issue encourage adoption of advanced prevention measures.

  • Substantial burden and cost: SSIs add hospital days and costs, and patients who develop them are far more likely to need intensive care or be readmitted.

  • No approved SSI-specific products in major markets: A large unmet need creates room for new approvals.

  • Late-stage pipeline progress: D-PLEX100 has an NDA under review and a potential 2027 decision, with XF-73 and STERIWAVE advancing.

  • Regulatory support: Fast Track, Breakthrough Therapy, and QIDP designations accelerate development and add exclusivity.

Learn about new drugs, pipeline developments, and key players with DelveInsight’s expert analysis @ Surgical Site Infections market research

Surgical Site Infections Market Barriers

  • Entrenched standard of care: Low-cost perioperative antibiotics, antiseptic preparation, and infection-control bundles are well established and widely used.

  • Variable risk across procedures: Wide differences in SSI incidence by procedure and surveillance method complicate trial design and targeting.

  • Few late-stage candidates: Only a small number of products are near approval, so regulatory outcomes carry concentrated risk.

  • Demonstrating value: New products must show meaningful infection reductions and fit surgical workflows to justify added cost.

  • Cost and reimbursement pressure: Hospitals and payers scrutinize add-on prevention products, particularly in bundled payment settings.

  • Antimicrobial resistance: Resistance can limit the effectiveness of antibiotic-based prevention strategies.

  • Prevention bundles over single products: Experts note that reducing SSI rates depends on comprehensive bundles rather than any one intervention.

Scope of the Surgical Site Infections Report

  • Coverage: 7MM (US, EU4, UK, Japan)

  • Companies: As listed above

  • Therapies: Olanexidine gluconate (OLANEDINE), D-PLEX100, XF-73, STERIWAVE, and others

  • Assessment by Product Type: Mono, Combination, Mono/Combination

  • Assessment by Clinical Stage: Discovery, Pre-clinical, Phase I, Phase II, Phase III

Download DelveInsight’s in-depth Surgical Site Infections report today! @ Surgical Site Infections market insight

Table of Contents

  1. Introduction

  2. Executive Summary

  3. Surgical Site Infections: Overview

  4. Pipeline Therapeutics

  5. Therapeutic Assessment

  6. DelveInsight’s Analytical Perspective

  7. Late Stage Products (Phase III): D-PLEX100 (PolyPid), STERIWAVE (Ondine)

  8. Mid Stage Products (Phase II): XF-73 (AMR Bio), Phase II/III

  9. Early Stage Products (Phase I): None currently

  10. Preclinical and Discovery Stage Products

  11. Inactive Products

  12. Key Companies

  13. Key Products

  14. Unmet Needs

  15. Market Drivers and Barriers

  16. Future Perspectives and Conclusion

  17. Analyst Views

  18. Appendix

  19. About Us

About DelveInsight DelveInsight is a leading healthcare-focused market research and consulting firm that provides clients with high-quality market intelligence and analysis to support informed business decisions. With a team of experienced industry experts and a deep understanding of the life sciences and healthcare sectors, we offer customized research solutions and insights to clients across the globe.

Media Contact
Company Name: DelveInsight Business Research LLP
Contact Person: Mehul Malhotra
Email:Send Email
Phone: 09650213330
Address:A-1 NV 89107
City: delhi
State: Indiana
Country: United States
Website: https://www.delveinsight.com/consulting

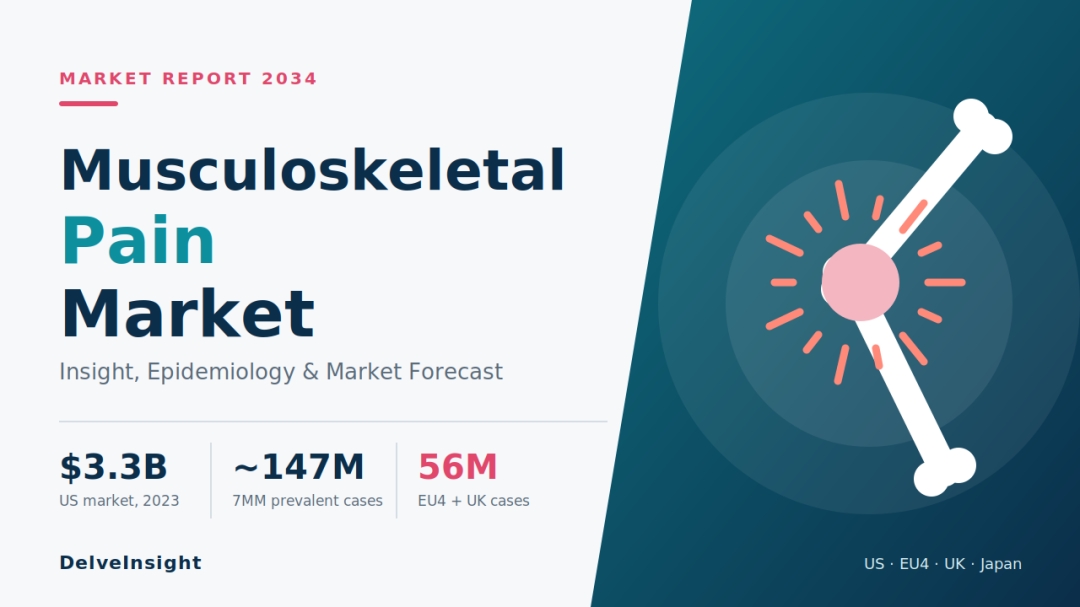
Musculoskeletal Pain Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight

Musculoskeletal Pain Market and Pipeline Appear Robust With Key Pharma Companies Actively Working in the Therapeutics Segment | DelveInsight
The Musculoskeletal Pain market analysis report delivers important insights into ongoing research on pipeline Musculoskeletal Pain drugs, clinical strategies, upcoming therapeutics, and commercial analysis.

(Albany, US) On November 02, 2026, DelveInsight’s “Musculoskeletal Pain Market Insights, Epidemiology and Market Forecast – 2036” report provides comprehensive insights into the Musculoskeletal Pain market and pipeline landscape across the 7MM. It covers marketed and emerging drug profiles, including clinical and nonclinical stage products. It also covers the therapeutics assessment by product type, stage, route of administration, and molecule type, and examines the market drivers and barriers shaping the space.

Discover the latest drugs and treatment options in the Musculoskeletal Pain Pipeline @ https://www.delveinsight.com/report-store/musculoskeletal-pain-market

Key Takeaways from the Musculoskeletal Pain Report

  • In April 2026, Taiwan Liposome Company reported exploratory Phase III data for TLC599 at OARSI 2026, suggesting it may reduce joint structural deterioration and reinforcing its potential as a disease-modifying osteoarthritis therapy.

  • In April 2026, Mesoblast outlined milestones for rexlemestrocel-L in chronic low back pain (CLBP): completion of pivotal trial enrollment by the end of April 2026, topline data in mid-2027, a BLA submission in Q3 2027, and potential FDA approval and US launch in Q2 2028. In January 2026, the company received FDA feedback on a potential BLA.

  • In January 2026, Biosplice Therapeutics announced it had submitted an NDA to the FDA for lorecivivint for the treatment of knee osteoarthritis.

  • ZILRETTA generated USD 116.6 million in sales in 2025, showing continued demand for localized non-opioid pain management.

  • Musculoskeletal conditions affect about 1.7 billion people globally, and musculoskeletal pain affects almost 37% of the US population.

  • DelveInsight’s report depicts a space shifting from symptomatic care toward non-opioid analgesics, regenerative medicine, and potential disease-modifying osteoarthritis drugs (DMOADs).

  • Leading Musculoskeletal Pain companies include Flexion, Taisho Pharmaceutical, Bioventus, Mesoblast, Taiwan Liposome Company, Biosplice, Centrexion Therapeutics, and others.

  • Promising therapies include ZILRETTA, LOQOA TAPE, TLC599, DUROLANE, CNTX-0066, rexlemestrocel-L (MPC-06-ID), lorecivivint (SM04690), and others.

Get insights into clinical trials, emerging therapies, and leading companies with DelveInsight @ Musculoskeletal Pain market

Musculoskeletal Pain Overview

Musculoskeletal pain arises from the muscles, bones, joints, tendons, ligaments, and other supporting structures. It includes conditions such as osteoarthritis, low back pain, neck pain, rheumatoid arthritis, and sports-related injuries, and low back pain is the leading cause of disability worldwide in Global Burden of Disease studies. Prevalence rises with age, obesity, sedentary lifestyles, and occupational risk factors. Diagnosis rests on clinical evaluation and history, supported by X-ray, MRI, CT, ultrasound, and, for suspected inflammatory conditions, tests such as ESR, CRP, rheumatoid factor, and anti-CCP. Treatment is multimodal and stepwise. It starts with exercise, physiotherapy, and weight reduction, plus NSAIDs (oral or topical) and acetaminophen. Muscle relaxants, short-term opioids, corticosteroid injections, and nerve blocks are used in selected cases, and surgery is reserved for advanced or refractory disease.

Common symptoms include:

  • Pain, stiffness, and weakness

  • Swelling, warmth, and tenderness

  • Joint noises and decreased range of motion

  • Reduced mobility and impaired quality of life

Learn about new drugs, pipeline developments, and key players with DelveInsight’s expert analysis @ Musculoskeletal Pain market insight

Musculoskeletal Pain Emerging Drugs Profile

Rexlemestrocel-L (MPC-06-ID): Mesoblast Rexlemestrocel-L is a mesenchymal precursor cell therapy delivered by intradiscal injection for chronic low back pain caused by disc degeneration. It targets patients who have exhausted conservative options, may have failed epidural steroid injections, and have no option other than invasive surgery. Its mechanism combines MSC-based regeneration with anti-inflammatory paracrine signaling. A BLA is planned for Q3 2027, with potential approval in Q2 2028. Currently, the drug is in Phase III.

TLC599: Taiwan Liposome Company TLC599 is a proprietary BioSeizer multilamellar, multivesicular lipid formulation of dexamethasone sodium phosphate, designed to provide fast onset and sustained pain relief for up to 24 weeks after intra-articular injection in osteoarthritis. Exploratory Phase III data presented at OARSI 2026 suggest a potential structural benefit. Currently, the drug is in Phase III.

Lorecivivint (SM04690): Biosplice Lorecivivint is an intra-articular Clk dual-specificity kinase inhibitor being developed for knee osteoarthritis. Biosplice submitted an NDA to the FDA in January 2026. Currently, the drug is in Phase III, with an NDA submitted.

CNTX-0066: Centrexion Therapeutics CNTX-0066 is an intra-articular TrkA receptor antagonist being developed for knee osteoarthritis pain. Currently, the drug is in Phase II.

Explore groundbreaking therapies and clinical trials in the Musculoskeletal Pain Pipeline @ Musculoskeletal Pain market research

Musculoskeletal Pain Market Drivers

  • Rising global burden: Musculoskeletal disorders are the leading cause of disability worldwide, and osteoarthritis and low back pain account for a large share of years lived with disability.

  • Aging population: Osteoarthritis, degenerative disc disease, and other chronic conditions increase significantly with age, sustaining demand for both symptomatic and disease-modifying treatments.

  • High unmet need: NSAIDs, corticosteroids, and viscosupplements mainly provide symptomatic relief and have limited effect on disease progression.

  • Shift to non-opioid management: Concerns about dependence, overdose risk, and regulatory restrictions are accelerating adoption of non-opioid analgesics, localized therapies, and regenerative medicine.

  • Late-stage pipeline progress: Three candidates are in Phase III, with an NDA submitted for lorecivivint and a potential 2028 launch for rexlemestrocel-L.

  • Longer-acting, convenient options: Single-injection and sustained-release products, such as DUROLANE and TLC599, may offer advantages in patient convenience and economics.

  • Rising obesity and sedentary lifestyles: These factors are expanding the at-risk population.

Musculoskeletal Pain Market Barriers

  • Entrenched standard of care: Low-cost NSAIDs, acetaminophen, physiotherapy, and exercise are well established and guideline-supported.

  • Safety limits of current drugs: Gastrointestinal, cardiovascular, and renal toxicities with long-term NSAIDs, and the limited durability of corticosteroid and hyaluronic acid injections, constrain use.

  • Mostly investigational disease-modifying options: Regenerative and DMOAD candidates remain unproven in practice, and demonstrating structural benefit alongside pain relief is difficult.

  • Heterogeneous conditions and subjective endpoints: Varied causes and pain-based outcomes complicate trial design and patient stratification.

  • Lack of biomarkers: Better patient stratification tools are still needed.

  • Crowded injectable market: Established products such as ZILRETTA, DUROLANE, and Synvisc-One compete for the same patients.

  • Reimbursement and cost pressure: Payers scrutinize high-cost injectables and cell therapies against inexpensive alternatives.

Scope of the Musculoskeletal Pain Report

  • Coverage: 7MM (US, EU4, UK, Japan)

  • Companies: As listed above

  • Therapies: ZILRETTA, LOQOA TAPE, TLC599, DUROLANE, CNTX-0066, rexlemestrocel-L (MPC-06-ID), lorecivivint (SM04690), and others

  • Assessment by Product Type: Mono, Combination, Mono/Combination

  • Assessment by Clinical Stage: Discovery, Pre-clinical, Phase I, Phase II, Phase III

Download DelveInsight’s in-depth Musculoskeletal Pain report today! @ Musculoskeletal Pain market trends

Table of Contents

  1. Introduction

  2. Executive Summary

  3. Musculoskeletal Pain: Overview

  4. Pipeline Therapeutics

  5. Therapeutic Assessment

  6. DelveInsight’s Analytical Perspective

  7. Late Stage Products (Phase III): Rexlemestrocel-L (Mesoblast), TLC599 (Taiwan Liposome Company), Lorecivivint (Biosplice)

  8. Mid Stage Products (Phase II): CNTX-0066 (Centrexion Therapeutics)

  9. Early Stage Products (Phase I): None currently

  10. Preclinical and Discovery Stage Products

  11. Inactive Products

  12. Key Companies

  13. Key Products

  14. Unmet Needs

  15. Market Drivers and Barriers

  16. Future Perspectives and Conclusion

  17. Analyst Views

  18. Appendix

  19. About Us

About DelveInsight DelveInsight is a leading healthcare-focused market research and consulting firm that provides clients with high-quality market intelligence and analysis to support informed business decisions. With a team of experienced industry experts and a deep understanding of the life sciences and healthcare sectors, we offer customized research solutions and insights to clients across the globe.

Media Contact
Company Name: DelveInsight Business Research LLP
Contact Person: Mehul Malhotra
Email:Send Email
Phone: +19193216187
Address:304 S. Jones Blvd #2432 NV 89107
City: Albany
State: New York
Country: United States
Website: https://www.delveinsight.com/consulting
Urothelial Carcinoma Market is Projected to Boom by 2036 Owing to the Increasing Adoption of Immunotherapies and Antibody-Drug Conjugates | DelveInsight

Urothelial Carcinoma Market is Projected to Boom by 2036 Owing to the Increasing Adoption of Immunotherapies and Antibody-Drug Conjugates | DelveInsight
The market dynamics for Urothelial Carcinoma are witnessing significant growth, driven by the rising incidence of bladder cancer, increasing adoption of targeted therapies and immunotherapies, and growing demand for effective treatment options for advanced and metastatic disease.

(Albany, US) - November 02, 2026 - The market dynamics for Urothelial Carcinoma are witnessing significant growth, driven by the rising incidence of bladder cancer, increasing adoption of targeted therapies and immunotherapies, and growing demand for effective treatment options for advanced and metastatic disease. Additionally, the development of emerging therapies such as Disitamab Vedotin (AIDIXI), TYRA-300 (Dabogratinib), UGN-104, and others is expected to further fuel the market.

DelveInsight, a leading market research firm, announces the release of its latest report, “DelveInsight’s Urothelial Carcinoma Market Insights, Epidemiology, and Market Forecast – 2036.” This comprehensive report provides an in-depth understanding of Urothelial Carcinoma, including historical and forecasted epidemiology, market trends, and treatment scenarios across the United States, EU4 (Germany, Spain, Italy, France), the United Kingdom, and Japan.

Key Takeaways from the Urothelial Carcinoma Market

  • The Urothelial Carcinoma market size across the 7MM is expected to grow significantly by 2036, driven by the increasing adoption of novel therapies and evolving treatment approaches.

  • The United States accounted for the largest Urothelial Carcinoma treatment market size in the 7MM in 2025, compared with EU4 countries, the United Kingdom, and Japan.

  • According to DelveInsight's estimates, approximately 206,300 incident cases of Urothelial Carcinoma existed across the 7MM in 2025.

  • In EU4 and the UK, males accounted for nearly 75% of incident cases of Urothelial Carcinoma in 2025, compared with females.

  • The median age at diagnosis of Urothelial Carcinoma is approximately 69 years in men and 71 years in women.

  • In the United States, approximately 50% of patients had TP53 mutations, followed by FGFR3 mutations in nearly 30% of patients in 2025.

  • Nearly all cases of urothelial carcinoma originate in the bladder, while upper tract urothelial carcinoma accounts for approximately 5–10% of urothelial malignancies.

  • Leading Urothelial Carcinoma companies, such as Bristol Myers Squibb, Astellas, Pfizer, AstraZeneca, Tyra Biosciences, UroGen Pharma, Johnson & Johnson, Taiho Oncology, and others, are developing new treatment options.

  • Promising Urothelial Carcinoma therapies include Enfortumab Vedotin-ejfv (PADCEV), Pembrolizumab (KEYTRUDA), Nivolumab (OPDIVO), Erdafitinib (BALVERSA), UGN-104, Disitamab Vedotin (AIDIXI), Durvalumab + Tremelimumab, and TYRA-300.

Keen to know more about the market? Request our sample page athttps://www.delveinsight.com/sample-request/urothelial-carcinoma-market

Key Factors Driving the Urothelial Carcinoma Market

Rising Incidence and Disease Burden of Urothelial Carcinoma: The increasing incidence of bladder cancer, particularly among the aging population, is a major factor driving the Urothelial Carcinoma market. Urothelial carcinoma accounts for nearly 90% of bladder cancer cases. Risk factors such as smoking, occupational exposure to chemicals, chronic bladder inflammation, and rising recurrence rates continue to contribute to the growing disease burden, increasing demand for effective long-term treatment options.

Increasing Focus on Personalized and Biomarker-Driven Treatment Approaches: Growing emphasis on precision medicine and biomarker testing is driving the adoption of personalized treatment strategies in Urothelial Carcinoma. The identification of actionable mutations, particularly FGFR alterations, is helping physicians optimize treatment selection and expand the eligible patient population for targeted therapies such as Erdafitinib (BALVERSA) and emerging candidates.

Robust Pipeline and Novel Combination Strategies: The Urothelial Carcinoma pipeline remains highly competitive, with pharmaceutical companies actively developing next-generation immunotherapies, targeted therapies, antibody-drug conjugates (ADCs), and combination regimens. Ongoing clinical trials focused on improving response durability, overcoming treatment resistance, and expanding treatment options for advanced disease are expected to strengthen the market.

Urothelial Carcinoma Competitive Landscape

Several Urothelial Carcinoma drugs in development include Disitamab Vedotin (AIDIXI) (Pfizer/RemeGen), TYRA-300 (Dabogratinib) (Tyra Biosciences), UGN-104 (UroGen Pharma), and 9MW2821 (Mabwell).

These candidates target different mechanisms and treatment needs. Disitamab Vedotin is an antibody-drug conjugate designed to deliver a cytotoxic agent to HER2-expressing tumor cells. TYRA-300 is a selective FGFR3 inhibitor being investigated in patients with FGFR3-altered advanced or metastatic urothelial carcinoma. UGN-104 is being developed for low-grade upper tract urothelial carcinoma, while 9MW2821 is being investigated in combination with toripalimab.

Discover more about therapies set to grab major Urothelial Carcinoma market share @ Urothelial Carcinoma Treatment Landscape

Recent Developments in the Urothelial Carcinoma Market

  • In April 2026, Mabwell announced that it would present the latest clinical data on 9MW2821 in combination with toripalimab for Urothelial Carcinoma through oral and poster presentations at ASCO 2026.

  • In November 2025, the US FDA approved pembrolizumab in combination with enfortumab vedotin-ejfv (PADCEV) as perioperative treatment for cisplatin-ineligible patients with muscle-invasive bladder cancer (MIBC).

  • In June 2025, data on nivolumab (OPDIVO) plus ipilimumab (YERVOY) for cisplatin-ineligible metastatic Urothelial Carcinoma, presented at ASCO 2025, did not demonstrate an overall survival improvement.

  • In April 2025, UroGen Pharma initiated a Phase III clinical trial of UGN-104 for the treatment of patients with low-grade upper tract Urothelial Carcinoma.

  • In February 2025, Pfizer and Astellas announced updated results from the Phase III EV-302 (KEYNOTE-A39) trial, demonstrating sustained overall survival and progression-free survival benefits with PADCEV plus KEYTRUDA in previously untreated locally advanced or metastatic Urothelial Carcinoma.

What is Urothelial Carcinoma?

Urothelial Carcinoma is a type of cancer that develops in the urothelial cells lining the urinary tract, including the bladder, renal pelvis, ureters, and urethra. It is the most common form of bladder cancer and accounts for more than 90% of bladder cancer cases in Europe.

The disease encompasses a broad clinical spectrum, ranging from low-grade non-muscle-invasive tumors to high-grade muscle-invasive and metastatic disease. Non-muscle-invasive Urothelial Carcinoma is generally managed through transurethral resection of bladder tumor (TURBT), followed by intravesical treatments such as Bacillus Calmette–Guérin (BCG) or chemotherapy. Muscle-invasive disease may require radical cystectomy and platinum-based chemotherapy, while advanced and metastatic disease can be treated with immunotherapies, targeted therapies, and antibody-drug conjugates.

Urothelial Carcinoma Epidemiology Segmentation

The Urothelial Carcinoma epidemiology section provides insights into the historical and current patient pool and forecasted trends across the leading markets. The Urothelial Carcinoma market report proffers epidemiological analysis for the study period 2022–2036 in the 7MM, segmented into:

  • Total Incident Cases of Urothelial Carcinoma

  • Gender-specific Incident Cases of Urothelial Carcinoma

  • Age-specific Incident Cases of Urothelial Carcinoma

  • Mutation-specific Incident Cases of Urothelial Carcinoma

  • Stage-specific Incident Cases (localized, regional, and distant/metastatic) of Urothelial Carcinoma

  • Line-wise Treated Cases of Urothelial Carcinoma

Scope of the Urothelial Carcinoma Market Report

  • Therapeutic Assessment: Urothelial Carcinoma current marketed and emerging therapies.

  • Urothelial Carcinoma Market Dynamics: Key market forecast assumptions, emerging therapies, and market outlook.

  • Key Companies: Bristol Myers Squibb, Astellas, Pfizer, AstraZeneca, Tyra Biosciences, UroGen Pharma, Johnson & Johnson, Taiho Oncology, and others.

  • Key Therapies: Enfortumab Vedotin-ejfv (PADCEV), Pembrolizumab (KEYTRUDA), Nivolumab (OPDIVO), Erdafitinib (BALVERSA), UGN-104, Disitamab Vedotin (AIDIXI), Durvalumab + Tremelimumab, TYRA-300, and others.

  • Competitive Intelligence Analysis: SWOT analysis, clinical pipeline assessment, and market-entry strategies.

  • Unmet Needs, KOL Views, Analyst Views, Urothelial Carcinoma Market Access, and Reimbursement.

To know more about Urothelial Carcinoma companies working in the treatment market, visit @ Urothelial Carcinoma Clinical Trials and Therapeutic Assessment

Table of Contents

  1. Urothelial Carcinoma Market Report Introduction

  2. Executive Summary for Urothelial Carcinoma

  3. SWOT Analysis of Urothelial Carcinoma

  4. Urothelial Carcinoma Patient Share (%) Overview at a Glance

  5. Urothelial Carcinoma Market Overview at a Glance

  6. Urothelial Carcinoma Background and Overview

  7. Urothelial Carcinoma Epidemiology and Patient Population

  8. Country-specific Patient Population of Urothelial Carcinoma

  9. Urothelial Carcinoma Current Treatment and Medical Practices

  10. Urothelial Carcinoma Unmet Needs

  11. Urothelial Carcinoma Emerging Therapies

  12. Urothelial Carcinoma Market Outlook

  13. Country-wise Urothelial Carcinoma Market Analysis (2022–2036)

  14. Urothelial Carcinoma Market Access and Reimbursement of Therapies

  15. Urothelial Carcinoma Market Drivers

  16. Urothelial Carcinoma Market Barriers

  17. Urothelial Carcinoma Appendix

  18. Urothelial Carcinoma Report Methodology

  19. DelveInsight Capabilities

  20. Disclaimer

  21. About DelveInsight

About DelveInsight

DelveInsight is a leading market research and consulting firm specializing in the life sciences and healthcare industries. Founded in 2014, the company provides comprehensive market intelligence, epidemiology, and insights across pharmaceuticals, biotechnology, medical devices, and emerging therapies. DelveInsight helps healthcare organizations make informed strategic decisions through data-driven research and industry expertise.

Media Contact
Company Name: DelveInsight Business Research LLP
Contact Person: Kirti Sharma
Email:Send Email
Phone: +19193216187
Address:304 S. Jones Blvd #2432
City: Albany
State: New York
Country: United States
Website: https://www.delveinsight.com/consulting

Chronic Smell and Flavor Loss Market is Projected to Witness Significant Growth by 2036 Owing to the Advancement of Novel Neuro-Regenerative Therapies | DelveInsight

Chronic Smell and Flavor Loss Market is Projected to Witness Significant Growth by 2036 Owing to the Advancement of Novel Neuro-Regenerative Therapies | DelveInsight
The market dynamics for Chronic Smell and Flavor Loss are witnessing steady growth, driven by the rising burden of post-viral olfactory dysfunction, increasing diagnosis and clinical awareness, and growing demand for effective treatment options. Additionally, the development of emerging therapies such as CYR-064 (Cyrano Therapeutics) is expected to create new opportunities in the market.

(Albany, US) On November 02, 2026 – The market dynamics for Chronic Smell and Flavor Loss are witnessing steady growth, driven by the rising burden of post-viral olfactory dysfunction, increasing diagnosis and clinical awareness, and growing demand for effective treatment options. Additionally, the development of emerging therapies such as CYR-064 (Cyrano Therapeutics) is expected to create new opportunities in the market.

DelveInsight, a leading market research firm, announces the release of its latest report, “DelveInsight’s Chronic Smell and Flavor Loss Market Insights, Epidemiology, and Market Forecast – 2036.” This comprehensive report provides an in-depth understanding of Chronic Smell and Flavor Loss, including historical and forecasted epidemiology, market trends, and treatment scenarios across the United States, EU4 (Germany, Spain, Italy, France), the United Kingdom, and Japan.

Key Takeaways from the Chronic Smell and Flavor Loss Market

  • According to DelveInsight’s analysis, the Chronic Smell and Flavor Loss market size was approximately USD 3,000 million in the 7MM in 2025.

  • The United States accounted for the largest share of the Chronic Smell and Flavor Loss market in 2025.

  • The market is expected to witness further growth during the forecast period of 2026–2036, supported by increasing disease recognition and the development of novel therapies.

  • Females had a higher prevalence of chronic smell and flavor loss than males across the 7MM in 2025.

  • Chronic smell and flavor loss can occur following viral infections, including COVID-19, and may also be associated with sinonasal diseases, neurological injury, medication effects, autoimmune conditions, and environmental exposures.

  • Currently, no FDA-approved disease-modifying therapies specifically target chronic smell and flavor loss. Management remains largely supportive and includes olfactory training and treatment of underlying sinonasal inflammation.

  • Leading companies, such as Cyrano Therapeutics, are working on innovative treatment approaches to address persistent olfactory dysfunction.

  • The promising emerging therapy in clinical development is CYR-064, an investigational intranasal therapy developed by Cyrano Therapeutics.

Keen to know more about the market? Request our sample page athttps://www.delveinsight.com/sample-request/chronic-smell-and-flavor-loss-market

Key Factors Driving the Chronic Smell and Flavor Loss Market

Rising Post-Viral Disease Burden: Chronic smell and flavor loss has gained significant attention following the COVID-19 pandemic, which made olfactory dysfunction one of the commonly reported persistent post-viral symptoms. Although most patients recover, a subset experiences long-term impairment, expanding the population requiring continued diagnosis, monitoring, and treatment.

Increasing Diagnosis and Clinical Awareness: Growing awareness of olfactory and gustatory disorders, post-COVID screening, and improved ENT evaluation practices are contributing to higher recognition of chronic sensory dysfunction. Objective smell tests, including UPSIT and Sniffin’ Sticks, can identify impairments that may not be accurately captured through patient self-reports.

Growing Focus on Neuro-Regenerative Treatment Approaches: The development of regenerative and neuro-restorative therapies is creating new opportunities in the Chronic Smell and Flavor Loss market. Investigational approaches such as CYR-064 aim to improve olfactory function by targeting cellular signaling pathways involved in olfactory neuronal activity and recovery.

Chronic Smell and Flavor Loss Competitive Landscape

The Chronic Smell and Flavor Loss pipeline remains highly concentrated, with CYR-064 from Cyrano Therapeutics representing the leading investigational candidate highlighted in DelveInsight’s report.

CYR-064 is an intranasal therapy designed to improve olfactory and gustatory function in patients with persistent sensory loss. It utilizes phosphodiesterase (PDE) inhibition to increase local cyclic nucleotide signaling, including cAMP and cGMP, which may support olfactory neuronal function and recovery.

The candidate has completed Phase II clinical evaluation, with positive topline results from the FLAVOR trial announced in February 2026. These results supported the company's planned progression into Phase III development in the second half of 2026.

Discover more about therapies set to shape the Chronic Smell and Flavor Loss market @ Chronic Smell and Flavor Loss Treatment Landscape

Recent Developments in the Chronic Smell and Flavor Loss Market

  • In July 2026, Cyrano Therapeutics announced that results from its Phase II FLAVOR clinical trial evaluating CYR-064 would be featured in an oral presentation at the 72nd Annual Meeting of the American Rhinologic Society in October 2026. The study evaluated the intranasal therapy in patients with persistent post-viral loss of smell across 14 clinical trial sites in the United States.

  • In February 2026, Cyrano Therapeutics announced positive topline results from its Phase II FLAVOR trial of CYR-064, an investigational intranasal soft-mist spray for persistent post-viral loss of smell (hyposmia). The results supported planned progression into Phase III development in the second half of 2026.

  • In June 2025, Cyrano Therapeutics announced its participation in the BIO International Convention, where discussions with potential partners and investors focused on CYR-064 and its targeted intranasal delivery approach for post-viral hyposmia.

What is Chronic Smell and Flavor Loss?

Chronic Smell and Flavor Loss involves persistent impairment of olfactory and gustatory function. Olfactory dysfunction may present as anosmia, the complete loss of smell, or hyposmia, a reduced ability to smell. Gustatory dysfunction may involve reduced taste perception, distorted taste sensations, or complete loss of taste.

The condition can occur following viral infections, including COVID-19, and may also be associated with sinonasal diseases, neurological injury, medication effects, autoimmune conditions, and environmental exposures. Persistent symptoms can interfere with food enjoyment, appetite, nutrition, personal safety, and overall quality of life.

Diagnosis generally involves a detailed clinical history, examination by an ear, nose, and throat (ENT) specialist, and psychophysical testing. Validated tools such as the University of Pennsylvania Smell Identification Test (UPSIT) and Sniffin’ Sticks can help quantify olfactory function. Treatment depends on the underlying cause and may include olfactory training and management of associated sinonasal inflammation.

Chronic Smell and Flavor Loss Epidemiology Segmentation

The Chronic Smell and Flavor Loss epidemiology section provides insights into the historical and current patient pool and forecasted trends across the leading markets. The report evaluates epidemiological trends for the study period 2022–2036, segmented into:

  • Total Prevalent Cases of Chronic Smell and Flavor Loss

  • Total Diagnosed Cases of Chronic Smell and Flavor Loss

  • Gender-specific Diagnosed Cases (excluding COVID-19 patients) of Chronic Smell and Flavor Loss

  • Age-specific Diagnosed Cases (excluding COVID-19 patients) of Chronic Smell and Flavor Loss

  • Etiology-specific Diagnosed Cases (excluding COVID-19 patients) of Chronic Smell and Flavor Loss

  • Total Treated Cases of Chronic Smell and Flavor Loss

Scope of the Chronic Smell and Flavor Loss Market Report

  • Therapeutic Assessment: Chronic Smell and Flavor Loss current treatment practices and emerging therapies.

  • Chronic Smell and Flavor Loss Market Dynamics: Key market forecast assumptions, emerging therapies, and market outlook.

  • Key Company: Cyrano Therapeutics.

  • Key Therapy: CYR-064.

  • Epidemiology Analysis: Total prevalent cases, diagnosed cases, gender-specific cases, age-specific cases, etiology-specific cases, and treated cases.

  • Competitive Intelligence Analysis: Clinical development assessment, SWOT analysis, and market-entry opportunities.

  • Unmet Needs, KOL Views, Analyst Views, Market Access, and Reimbursement.

To know more about companies working in the Chronic Smell and Flavor Loss treatment market, visit @ Chronic Smell and Flavor Loss Clinical Trials and Therapeutic Assessment

Table of Contents

  1. Chronic Smell and Flavor Loss Market Report Introduction

  2. Executive Summary for Chronic Smell and Flavor Loss

  3. Key Events in Chronic Smell and Flavor Loss

  4. SWOT Analysis of Chronic Smell and Flavor Loss

  5. Chronic Smell and Flavor Loss Market Overview at a Glance

  6. Chronic Smell and Flavor Loss Background and Overview

  7. Chronic Smell and Flavor Loss Epidemiology and Patient Population

  8. Country-specific Patient Population of Chronic Smell and Flavor Loss

  9. Chronic Smell and Flavor Loss Current Treatment and Medical Practices

  10. Chronic Smell and Flavor Loss Unmet Needs

  11. Chronic Smell and Flavor Loss Emerging Therapies

  12. Chronic Smell and Flavor Loss Market Outlook

  13. Country-wise Chronic Smell and Flavor Loss Market Analysis (2022–2036)

  14. Chronic Smell and Flavor Loss Market Access and Reimbursement

  15. Chronic Smell and Flavor Loss Market Drivers

  16. Chronic Smell and Flavor Loss Market Barriers

  17. Chronic Smell and Flavor Loss KOL Views

  18. Chronic Smell and Flavor Loss SWOT and Conjoint Analysis

  19. Chronic Smell and Flavor Loss Appendix

  20. Chronic Smell and Flavor Loss Report Methodology

  21. About DelveInsi

DelveInsight is a leading market research and consulting firm specializing in the life sciences and healthcare industries. Founded in 2014, the company provides comprehensive market intelligence, epidemiology, and insights across pharmaceuticals, biotechnology, medical devices, and emerging therapies. DelveInsight helps healthcare organizations make informed strategic decisions through data-driven research and industry expertise.

Media Contact
Company Name: DelveInsight Business Research LLP
Contact Person: Kirti Sharma
Email:Send Email
Phone: +19193216187
Address:304 S. Jones Blvd #2432
City: Albany
State: New York
Country: United States
Website: https://www.delveinsight.com/consulting

Diabetic Foot Ulcers (DFUs) Market is Projected to Boom by 2036 Owing to the Rising Prevalence of Diabetes and Advancements in Regenerative Wound Care Therapies | DelveInsight

Diabetic Foot Ulcers (DFUs) Market is Projected to Boom by 2036 Owing to the Rising Prevalence of Diabetes and Advancements in Regenerative Wound Care Therapies | DelveInsight
The market dynamics for Diabetic Foot Ulcers (DFUs) are witnessing significant growth, driven by the rising prevalence of diabetes, increasing burden of chronic wounds, growing adoption of advanced wound care products, and rising demand for regenerative treatment approaches.

(Albany, US) On November 02, 2026 – The market dynamics for Diabetic Foot Ulcers (DFUs) are witnessing significant growth, driven by the rising prevalence of diabetes, increasing burden of chronic wounds, growing adoption of advanced wound care products, and rising demand for regenerative treatment approaches. Additionally, the development of emerging therapies such as PEP-TISSEEL (RION), Allo-APZ2-Diabetic Foot Ulcer (RHEACELL), ELU42 (Eluciderm), and others is expected to further fuel market growth.

DelveInsight, a leading market research firm, announces the release of its latest report, “DelveInsight’s Diabetic Foot Ulcer Market Insights, Epidemiology, and Market Forecast – 2036.” This comprehensive report provides an in-depth understanding of Diabetic Foot Ulcers, including historical and forecasted epidemiology, market trends, and treatment scenarios across the United States, EU4 (Germany, Spain, Italy, France), the United Kingdom, and Japan.

Key Takeaways from the Diabetic Foot Ulcer Market

  • The Diabetic Foot Ulcer market size across the 7MM was approximately USD 2.5 billion in 2025 and is anticipated to grow at a CAGR of approximately 10% during 2026–2036.

  • The United States accounted for the largest Diabetic Foot Ulcer market size, reaching approximately USD 2.3 billion in 2025.

  • According to DelveInsight's estimates, the total prevalent cases of Diabetic Foot Ulcer across the 7MM were approximately 6,600,000 in 2025.

  • The United States accounted for approximately 5,060,000 prevalent cases of Diabetic Foot Ulcer in 2025, representing the largest patient population among the 7MM.

  • Among the EU4 countries, Italy accounted for the highest number of prevalent Diabetic Foot Ulcer cases, followed by Germany, whereas Spain recorded the lowest number of cases in 2025.

  • The rising prevalence of diabetes, peripheral neuropathy, peripheral arterial disease, chronic kidney disease, obesity, and impaired wound healing is contributing to the growing disease burden.

  • Leading Diabetic Foot Ulcer companies, such as Integra Life Sciences, Lynch Regenerative Medicine, Smith & Nephew, RION, RHEACELL GmbH, FGK Clinical Research GmbH, Ticeba GmbH, and Eluciderm, are developing innovative treatment options.

  • Promising emerging therapies in the Diabetic Foot Ulcer pipeline include PEP-TISSEEL, Allo-APZ2-Diabetic Foot Ulcer, ELU42, and others.

Keen to know more about the market? Request our sample page athttp://delveinsight.com/sample-request/diabetic-foot-ulcers-dfus-market

Key Factors Driving the Diabetic Foot Ulcer Market

Rising Prevalence of Diabetes and Diabetic Foot Ulcers: The increasing prevalence of diabetes, particularly among the aging population, is contributing to the growing burden of diabetic foot ulcers. Long-standing or poorly controlled blood glucose levels can lead to peripheral neuropathy and vascular complications, increasing the risk of ulcer formation. The rising number of patients with chronic wounds is consequently driving demand for effective wound management and treatment options.

Increasing Adoption of Advanced Wound Care Therapies: The growing demand for advanced wound care solutions, including bioengineered skin substitutes, growth factors, negative pressure wound therapy, and regenerative products, is creating significant opportunities in the Diabetic Foot Ulcer market. These approaches aim to improve wound closure, support tissue regeneration, and reduce complications associated with chronic non-healing ulcers.

Growing Focus on Regenerative and Biologic Therapies: The development of cell-based therapies, exosome-based products, and novel wound-healing agents is transforming the Diabetic Foot Ulcer treatment landscape. Emerging candidates such as PEP-TISSEEL, Allo-APZ2-Diabetic Foot Ulcer, and ELU42 are being investigated to address impaired wound healing and improve tissue regeneration.

Diabetic Foot Ulcer Competitive Landscape

Several Diabetic Foot Ulcer therapies are in development, including PEP-TISSEEL (RION), Allo-APZ2-Diabetic Foot Ulcer (RHEACELL/FGK Clinical Research/Ticeba), and ELU42 (Eluciderm).

These candidates employ different therapeutic approaches, including exosome-based wound healing, allogeneic ABCB5-positive mesenchymal stromal cells, and Wnt pathway modulation. These innovative approaches aim to improve tissue regeneration, promote wound closure, and address the limitations associated with conventional wound management.

Leading companies operating in the Diabetic Foot Ulcer market include Integra Life Sciences, Lynch Regenerative Medicine, Smith & Nephew, RION, RHEACELL GmbH, FGK Clinical Research GmbH, Ticeba GmbH, and Eluciderm.

Discover more about therapies set to grab major Diabetic Foot Ulcer market share @ Diabetic Foot Ulcer Treatment Landscape

Recent Developments in the Diabetic Foot Ulcer Market

  • In September 2025, RION partnered with Lonza to enable cGMP manufacturing and scale-up of its PEP exosome therapy, leveraging Lonza's manufacturing expertise and Houston facility to support late-stage clinical supply and potential future commercial production.

  • In June 2025, Eluciderm received US FDA IND clearance for ELU42, a topical Wnt modulator with bacteriostatic properties, and announced the initiation of a Phase I/IIa clinical trial in August 2025 across three US sites to evaluate its safety and efficacy in Diabetic Foot Ulcers.

  • In March 2025, Lynch Regenerative Medicine acquired exclusive rights to REGRANEX gel and recombinant PDGF from Smith & Nephew to expand its applications beyond Diabetic Foot Ulcers into broader soft tissue regeneration and aesthetic wound healing.

  • In January 2025, RION announced the completion of patient enrollment in its Phase II clinical trial of PEP for Diabetic Foot Ulcers, building on encouraging Phase IB safety and efficacy data. The company indicated plans to advance to a Phase III study and pursue a BLA filing with the FDA if results are successful.

What are Diabetic Foot Ulcers?

Diabetic Foot Ulcers (DFUs) are open sores or wounds that develop on the feet of individuals with diabetes, commonly resulting from a combination of peripheral neuropathy, peripheral arterial disease, impaired circulation, and poor wound healing. These ulcers frequently occur on the plantar surface of the foot and can range from superficial skin lesions to deep wounds involving muscles and bones.

Peripheral neuropathy reduces sensation in the feet, making patients less likely to notice injuries, pressure, or minor trauma. At the same time, poor blood circulation and impaired immune function can delay wound healing and increase the risk of infection. In severe cases, diabetic foot ulcers can lead to osteomyelitis, hospitalization, and lower-limb amputation.

Diabetic Foot Ulcer Epidemiology Segmentation

The Diabetic Foot Ulcer epidemiology section provides insights into the historical and current patient pool and forecasted trends across the leading markets. The Diabetic Foot Ulcer market report provides epidemiological analysis for the study period 2022–2036 in the 7MM, segmented into:

  • Total Prevalent Cases of Diabetic Foot Ulcer

  • Total Diagnosed Prevalent Cases of Diabetic Foot Ulcer

  • Gender-specific Diagnosed Prevalent Cases of Diabetic Foot Ulcer

  • Age-specific Diagnosed Prevalent Cases of Diabetic Foot Ulcer

  • Severity/Chronicity of Wound-specific Diagnosed Prevalent Cases of Diabetic Foot Ulcer

  • Total Treated Cases of Diabetic Foot Ulcer

Scope of the Diabetic Foot Ulcer Market Report

  • Therapeutic Assessment: Current marketed and emerging Diabetic Foot Ulcer therapies.

  • Diabetic Foot Ulcer Market Dynamics: Key market forecast assumptions, emerging therapies, and market outlook.

  • Key Companies: Integra Life Sciences, Lynch Regenerative Medicine, Smith & Nephew, RION, RHEACELL GmbH, FGK Clinical Research GmbH, Ticeba GmbH, Eluciderm, and others.

  • Key Therapies: PEP-TISSEEL, Allo-APZ2-Diabetic Foot Ulcer, ELU42, OMNIGRAFT Dermal Regeneration Matrix, REGRANEX, and others.

  • Competitive Intelligence Analysis: SWOT analysis, clinical pipeline assessment, and market-entry opportunities.

  • Unmet Needs, KOL Views, Analyst Views, Diabetic Foot Ulcer Market Access, and Reimbursement.

To know more about Diabetic Foot Ulcer companies working in the treatment market, visit @ Diabetic Foot Ulcer Clinical Trials and Therapeutic Assessment

Table of Contents

  1. Diabetic Foot Ulcer Market Report Introduction

  2. Executive Summary of Diabetic Foot Ulcer

  3. SWOT Analysis of Diabetic Foot Ulcer

  4. Diabetic Foot Ulcer Patient Share (%) Overview at a Glance

  5. Diabetic Foot Ulcer Market Overview at a Glance

  6. Diabetic Foot Ulcer Background and Overview

  7. Diabetic Foot Ulcer Epidemiology and Patient Population

  8. Country-specific Patient Population of Diabetic Foot Ulcer

  9. Diabetic Foot Ulcer Current Treatment and Medical Practices

  10. Diabetic Foot Ulcer Unmet Needs

  11. Diabetic Foot Ulcer Emerging Therapies

  12. Diabetic Foot Ulcer Market Outlook

  13. Country-wise Diabetic Foot Ulcer Market Analysis (2022–2036)

  14. Diabetic Foot Ulcer Market Access and Reimbursement of Therapies

  15. Diabetic Foot Ulcer Market Drivers

  16. Diabetic Foot Ulcer Market Barriers

  17. Diabetic Foot Ulcer Appendix

  18. Diabetic Foot Ulcer Report Methodology

  19. DelveInsight Capabilities

  20. Disclaimer

  21. About DelveInsight

About DelveInsight

DelveInsight is a leading market research and consulting firm specializing in the life sciences and healthcare industries. Founded in 2014, the company provides comprehensive market intelligence, epidemiology, and insights across pharmaceuticals, biotechnology, medical devices, and emerging therapies. DelveInsight helps healthcare organizations make informed strategic decisions through data-driven research and industry expertise.

Media Contact
Company Name: DelveInsight Business Research LLP
Contact Person: Kirti Sharma
Email:Send Email
Phone: +19193216187
Address:304 S. Jones Blvd #2432
City: Albany
State: New York
Country: United States
Website: https://www.delveinsight.com/consulting